
Luxury, makeup, fragrance and hair
Tmall, Douyin and Xiaohongshu storefronts built and run for cosmetics brands entering China
The platform question changed in 2025. Douyin overtook Tmall as the top GMV driver for beauty e-commerce in China, though Tmall still holds 44-50% of major online retail beauty GMV and remains the safer entry point for brands that need the trust signal of an official flagship store. Which one is right for you depends on budget and product type, not on which one is trendier this quarter.
Registration rules tightened too. Once a brand's annual cross-border e-commerce (CBEC) sales exceed RMB 1 million on a given platform, Chinese regulators now expect compliance closer to general trade import requirements, not the lighter CBEC filing that used to cover most new entrants. Special-use cosmetics, sunscreen, hair dye, anti-hair-loss and whitening products, now need NMPA registration once you cross that volume, even under CBEC. Only products whose HS code sits on the official positive list, 26 cosmetic categories including masks, shampoo and perfume, can even use the CBEC channel at all.
Once registered, your store needs to be built for how Chinese shoppers actually decide: dense product descriptions, full ingredient lists, and photos that answer every question before a customer has to ask a live chat agent. Every major platform runs its own calendar of shopping festivals, and shoppers expect a brand to show up with a real offer on each one, not just a banner.
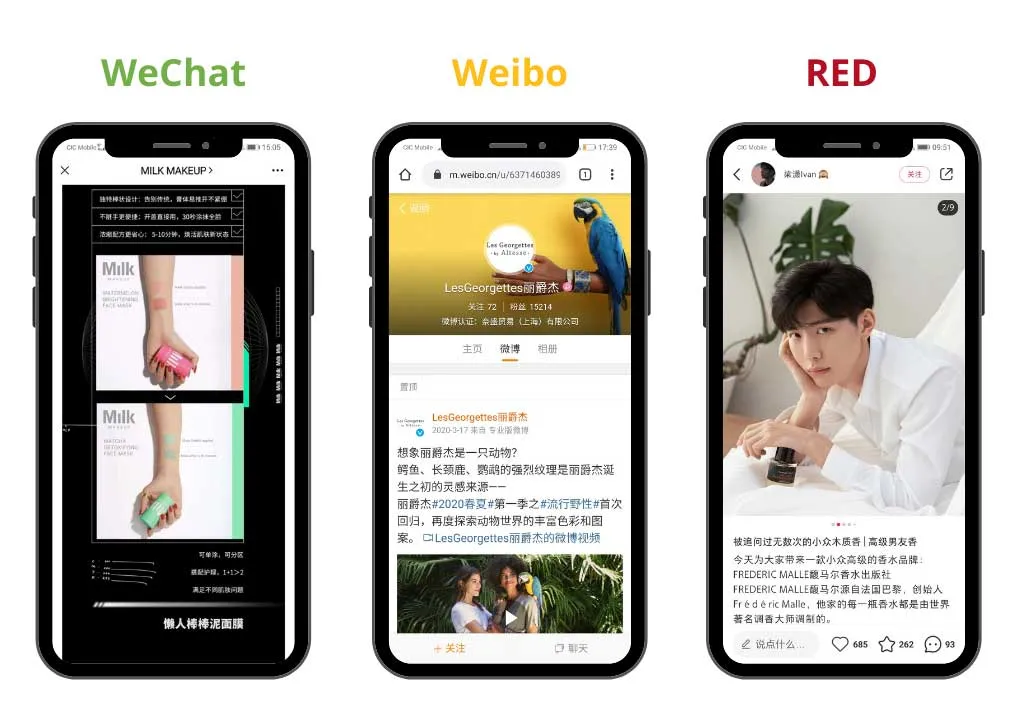
A storefront with no off-site presence does not sell. Xiaohongshu functions as a discovery and trust layer rather than a transaction platform: roughly 300 million monthly active users research a product on Xiaohongshu before buying it somewhere else, on Tmall, Douyin, JD or Pinduoduo. If your brand is invisible there, shoppers arrive at your store with no context and no reason to trust you over a domestic competitor.
Live commerce is where the money actually moves. China's live commerce market is on track to cross USD 1 trillion in 2026, led by Douyin and Kuaishou, and the average Chinese live-commerce buyer already spends far more per year than shoppers anywhere else. A single well-run livestream, with the right host and the right offer, can outsell a month of static listing traffic.
Off-site visibility is what makes the on-platform store convert once a shopper actually lands on it.
In detail
A complete market research and analysis of your budget and current status in China will help us choose the best Chinese eCommerce plateform to sell your products.
Registering on Chinese eCommerce apps can be a huge headache, let us take care of it, save you some time and money.
Design a beautiful store + listing & stock management
run in-app campaign, manage customer services
Ereputation is crucial for your conversion rate. Off-site marketing is the answer.
A detailed report so you know how your budget is spent & Optimisation
Why us
Letting an experienced agency handle registration should be reason enough. E-commerce in China is more competitive than it was even two years ago: Chinese domestic beauty brands now hold 57.4% of the total cosmetics market, a fifth straight year of share gains, and they are winning that share with platform-native pricing and formats that took foreign brands years to understand. Douyin overtaking Tmall for beauty GMV in 2025 is only the most visible sign of how fast the ground moves under this market.
Regulation adds a second layer most brands underestimate. The ICP Commercial License required to run your own transactional site in China can only be held by a 100%-Chinese-owned company, or a joint venture where foreign ownership is capped at 50%. Most foreign beauty brands cannot hold it outright, which is exactly why marketplace flagship stores, run through the right partner, are usually the faster path to market.
The discipline is the same at every brand size: audit first, pick the platform that fits the budget, then run registration, store and off-site promotion as one connected plan instead of three separate vendors.
Case studies
Luxury, makeup, fragrance and hair
Supplements, nutricosmetics and wellness
Skincare, dermocosmetics and beauty devices
Luxury, makeup, fragrance and hair
Supplements, nutricosmetics and wellness
Skincare, dermocosmetics and beauty devices
Questions
Not as your main channel, but it still helps. A standalone site cannot be your primary store because the ICP Commercial License needed to run one is capped at 50% foreign ownership, so most foreign brands route sales through marketplace flagship stores instead. What your own site does well is SEO visibility and a sense of legitimacy when a Chinese shopper checks whether your brand is real before buying on Tmall or Douyin.
Depends on your goal. Tmall still holds 44-50% of major online beauty GMV and remains the trust-building choice for a first official flagship store, especially for CBEC entry. Douyin overtook Tmall as the top GMV driver for beauty in 2025 through live commerce, but growth there slowed sharply by early 2026, down 1.13% year-on-year in February, a sign the platform is maturing rather than still exploding. A common approach is to launch a Tmall store for credibility and run Douyin live commerce for volume, rather than picking one over the other.
The big one: once a brand's annual CBEC sales exceed RMB 1 million on a platform, regulators now expect general trade-level compliance, not the lighter CBEC filing most new entrants used before. Special-use products, sunscreen, hair dye, anti-hair-loss, whitening, now need NMPA registration past that threshold. Only products on the official 26-category positive list can use CBEC at all. A new customs rule, GACC Decree No. 284, takes effect December 1, 2026 and formalizes risk-based inspection for cosmetics imports, so expect more consistent enforcement, not less.
Two separate ICP registrations exist: an ICP Filing for non-commercial sites, and the ICP Commercial License for any site that sells goods, takes payment or carries ads. Foreign companies cannot apply directly. You need an onshore vehicle, a WFOE, a joint venture, or a partner, before China's Ministry of Industry and Information Technology will even accept the application, and the commercial license itself is capped at 50% foreign ownership. Processing typically takes two to three months, and in 2026 a content-moderation plan and a PIPL-aligned privacy policy are standard checklist items, not optional extras.
Xiaohongshu drives discovery, not transactions: about 300 million monthly users research a product there before buying it on Tmall, Douyin, JD or Pinduoduo. If you are invisible on Xiaohongshu, shoppers land on your store with zero context. Live commerce is where volume comes from, China's live commerce market is on track to pass USD 1 trillion in 2026, led by Douyin and Kuaishou. The brands that win combine both: XHS content to build the intent, live commerce to close it.
It is not optional. Mobile accounts for over 65% of online sales in China, and live commerce spend per buyer there is the highest in the world, previously benchmarked around USD 1,550 per year per active buyer. A store that is not built mobile-first, with fast load times and a livestream-ready product page, is competing at a structural disadvantage before a single ad runs.
Two, mainly. First, compliance: the RMB 1 million CBEC threshold and the 26-category positive list mean brands can no longer treat cross-border as a permanent loophole around registration. Second, platform dependency risk: Temu's US daily users fell roughly 48% within two months in 2025 after the US ended a tariff exemption, a reminder that policy shifts outside China can hit a cross-border brand's traffic overnight. Brands need a local partner who tracks both sides of that risk, Chinese regulation and the platform's own policy shifts.
Tmall's requirements and budget threshold are high, and we generally do not recommend it as a first move for smaller brands. Xiaohongshu, Douyin's shop features, and Pinduoduo's cross-border channel (0 commission, 0 deductions on many listings) are more accessible starting points, and they lean into social commerce, letting a smaller brand build a reputation before committing to a full Tmall flagship build-out.
Start here
We will tell you what is achievable, which channel should lead, and what it will cost. Including the times the honest answer is “not yet”.
Contact us